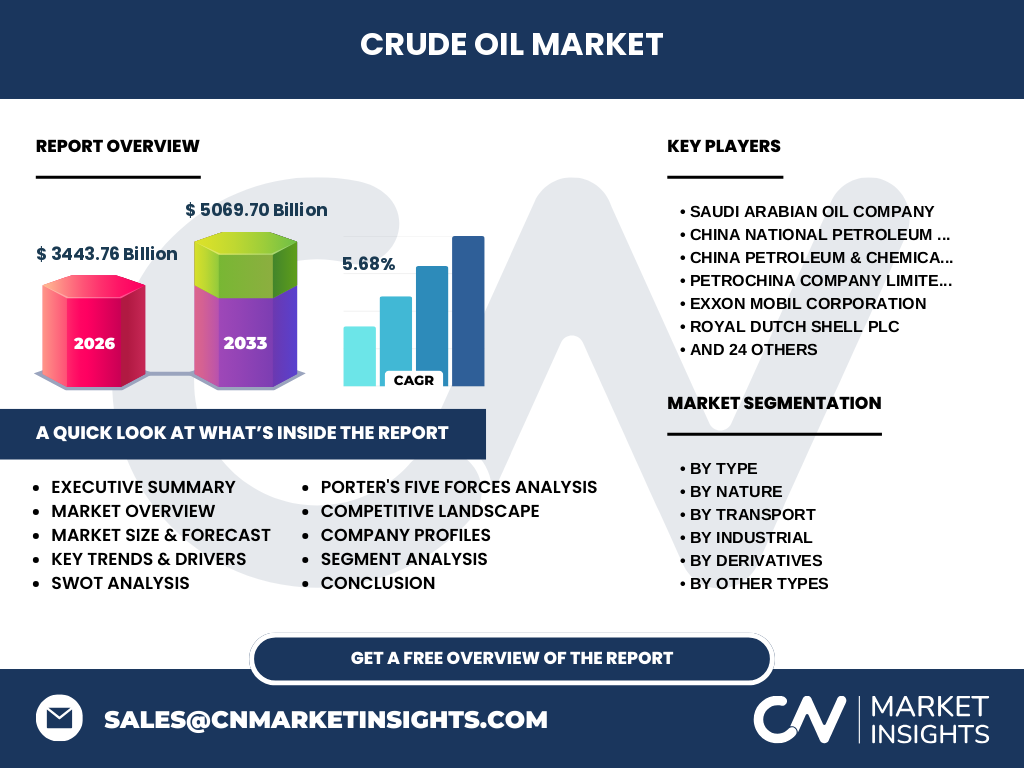
Market overview of the Crude Oil Market
Our analysis indicates that the Crude Oil Market is valued at 3443.76 Billion in 2026, serving as the foundational lifeblood of global energy and industrial infrastructure. This ecosystem encompasses the extraction, refining, and distribution of unrefined petroleum into high-value products like Aviation Fuel and Petrochemical Feedstock, managed by regulatory oversight from OPEC and the EIA across critical marine choke points like the Strait of Hormuz.
Structural Growth Drivers and Market Restraints
The market is propelled by surging industrialization and expanding mobility demands, yet faces severe headwinds from environmental mandates enforced by agencies such as the EPA and EU climate frameworks. Geopolitical instability in key supply corridors and volatile production quotas from state-owned enterprises introduce acute operational friction, challenging continuous supply chain integrity for major processors.
Emerging Industry Trends in the Crude Oil Market
A definitive pivot toward advanced digital reservoir modeling and enhanced oil recovery (EOR) techniques is reshaping upstream extraction workflows. Companies are increasingly deploying automated drilling telemetry and AI-driven pipeline monitoring to optimize output efficiency, mitigating carbon intensity while complying with tightening environmental disclosures.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic triggered an unprecedented demand collapse, forcing historic production shut-ins and testing storage capacities globally at terminals like Cushing, Oklahoma. The subsequent recovery trajectory has been characterized by resilient demand rebound across Automotive Fuel and Petrochemical Feedstock, though structural shifts in remote work permanently altered long-term distillate consumption curves.
Competitive Landscape and Strategic Dynamics
The competitive terrain features a mix of dominant national oil companies and supermajors—including Saudi Arabian Oil Company, Exxon Mobil Corporation, and China National Petroleum Corporation—controlling vast reserve bases. Market concentration remains high, with state-backed giants dictating global supply elasticity while integrated western firms accelerate vertical integration into low-carbon technologies.
Executive Summary of the Crude Oil Market
The Crude Oil Market demonstrates robust expansion fundamentals, with our research projecting a valuation of 5069.70 Billion by 2033 at a steady CAGR of 5.68%. Strategic positioning across high-yield derivatives like Naphthene and Aromatic fractions will remain critical for stakeholders navigating regulatory pressures and shifting macroeconomic tides.
Crude Oil Market Forecast (2027-2033)
Driven by sustained emerging market energy requirements, the market is set to expand significantly from its 2026 baseline to reach 5069.70 Billion by 2033, achieving a robust CAGR of 5.68%. This trajectory assumes steady industrial output expansion and sustained demand for Petrochemical Feedstock across Asian and Middle Eastern processing hubs.
Comprehensive Segmentation Analysis
Segmentation spans multiple dimensions: By Type (Transport, Industrial, Other Types), By Nature (Organic, Conventional), By Transport (Aviation Fuel, Marine Fuel, Gasoline, Diesel), By Industrial (Petrochemical Feedstock, Power Generation, Lubricants), By Derivatives (Paraffin, Naphthene, Aromatic, Asphaltic), and By Other Types (Residential Heating, Agricultural Fuel, Asphalt Production). Each category dictates distinct logistical requirements and refining margins.
Regional Market Distribution and Performance
Geographic performance highlights stark divergence, with the Middle East and Asia-Pacific regions driving volume growth through expanding refining capacities and industrial demand. Conversely, North America and Europe exhibit mature consumption profiles, focusing heavily on upgrading infrastructure efficiency and complying with strict environmental mandates governed by local jurisdictions.
In-Depth Regional Review
Asia-Pacific commands significant consumption share, anchored by refining powerhouses in China and India processing heavy crude grades for local manufacturing sectors. Meanwhile, Middle Eastern producers such as Saudi Arabian Oil Company and Abu Dhabi National Oil Company leverage low extraction costs to maintain formidable export dominance into key European and American markets.
Company Profiles and Strategic Positioning
Industry leaders such as Royal Dutch Shell plc, TotalEnergies SE, Chevron Corporation, and BP plc balance core upstream assets with strategic downstream diversification into renewables. Concurrently, regional titans like PetroChina Company Limited, Rosneft Oil Company, and Petrobras focus on securing ultra-deepwater and unconventional shale reserves to safeguard long-term production portfolios.
Porter's Five Forces Analysis
The Crude Oil Market experiences intense competitive rivalry among entrenched global producers, while buyer power remains moderate due to standardized commodity grading. Supplier power fluctuates based on OPEC quota decisions, and the persistent threat of substitution from alternative energy sources exerts long-term strategic pressure on capital allocation.
SWOT Analysis of the Industry
Strengths lie in unmatched global infrastructure networks and indispensable utility across Asphalt And Bitumen Production and Lubricants. Weaknesses involve high capital expenditure hurdles and regulatory vulnerabilities, while opportunities exist in digital field optimization and petrochemical integration, contrasted against threats from tightening carbon pricing policies.
Value Chain Analysis from Extraction to End-User
The value chain flows from upstream seismic exploration and drilling by firms like ConocoPhillips and Lukoil PJSC, through midstream marine transport via VLCC tankers, down to downstream catalytic cracking at facilities operated by ENI S.p.A. and PT Pertamina. Value capture is highest during periods of tight refining margins and constrained pipeline takeaway capacity.
Investment Insights and High-Potential Areas
Capital deployment should target advanced petrochemical integration projects and enhanced recovery technologies that maximize brownfield asset efficiency. Investors must prioritize firms demonstrating disciplined capital expenditure and robust compliance with emerging environmental standards across key operational jurisdictions like the North Sea and the Permian Basin.
Conclusion and Strategic Takeaways
Our analysis confirms that the Crude Oil Market remains an indispensable economic pillar, scaling toward 5069.70 Billion by 2033 at a 5.68% CAGR. Long-term success requires balancing traditional hydrocarbon extraction with aggressive technological modernization to navigate complex macroeconomic and regulatory environments.
Research Methodology and Data Triangulation
Baseline estimates are triangulated using a rigorous mix of primary stakeholder interviews with refining executives, trade registry data from organizations like the JODI database, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of segments such as Aviation Fuel and Agricultural Fuel across diverse geographic territories.
Scope of the Report and Coverage Parameters
This report evaluates the global Crude Oil Market across defined parameters, incorporating historical data from 2020 through a forecast horizon spanning 2027 to 2033. Coverage encompasses all primary product derivatives, regional consumption metrics, and competitive profiling of top-tier market participants without accounting for unforeseen geopolitical black-swan events.
Recent Developments and Strategic Industry Moves
Recent market activity highlights major capital investments in mega-refineries and petrochemical complexes by enterprises such as Kuwait Petroleum Corporation, Sonatrach SPA, and KazMunayGas. Strategic joint ventures focusing on low-carbon hydrogen integration and digital oilfield deployments continue to redefine operational paradigms across the sector.